Why One Missed Direct Debit Can Cost Your Business – and How Open Banking Saves You
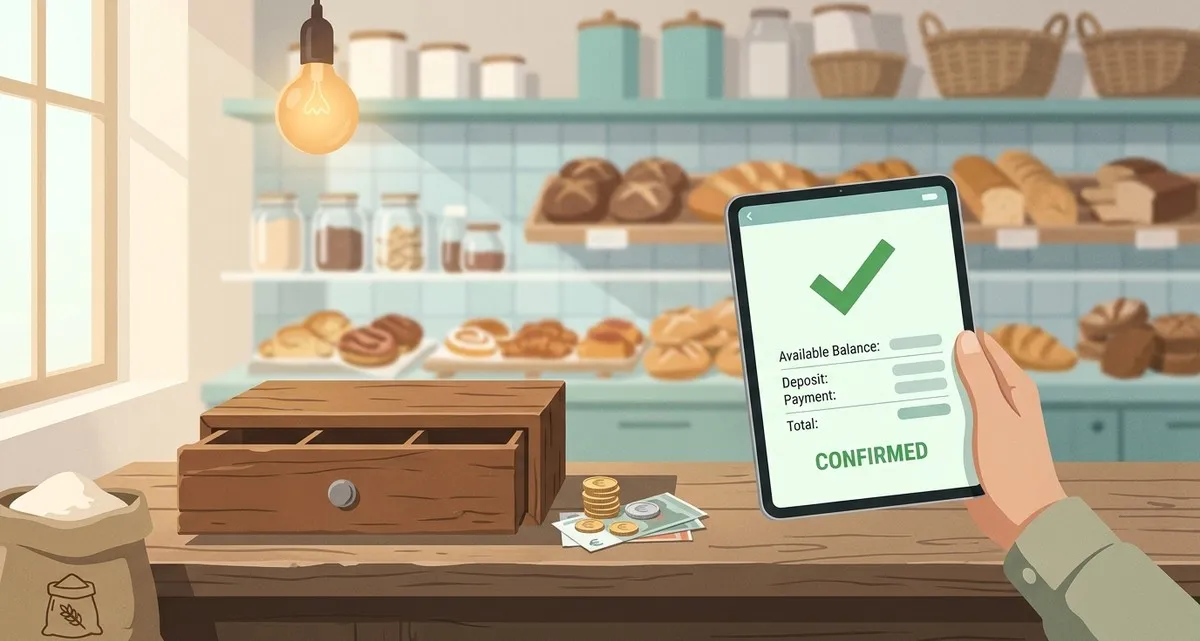
Why one missed direct debit can cost your business – and how to stop it
Imagine a bakery that expects €500 from a regular customer on the first of the month. The payment fails because the customer entered the wrong IBAN. The bakery now has to chase the payment, spends time on the phone, and risks a cash‑flow gap that could delay ordering fresh ingredients. For a small business, a single missed direct debit can quickly turn into lost sales, unhappy customers and extra administrative costs.
Open banking gives you a way to catch those mistakes before the money is taken. By using real‑time account information services (AIS) you can verify that the bank details are correct, check that there is enough balance, and even flag suspicious activity. The result? Fewer failed payments, less fraud, and smoother cash flow – all without needing a technical degree.
What open banking is and how it works for small businesses in the Netherlands
Open banking is a set of standards that let banks share customer‑approved data with third‑party providers through secure APIs. In practice, a customer can give you permission to:
- Read their bank account details (the IBAN and the name on the account).
- Check the account balance in real time.
- Confirm that the account belongs to the person who is paying.
All of this happens instantly, directly from the bank, and the data is encrypted end‑to‑end. For a Dutch business owner, the process feels familiar because Dutch consumers have been using direct‑bank payments and automatic incasso for decades. Open banking simply adds a digital layer that makes those payments safer and smarter.
Account Information Services (AIS) – the hidden power behind a simple payment
AIS is the technical name for the “read‑only” access described above. When you integrate an AIS solution, the checkout flow looks like this:
- The customer clicks “Pay by Bank”.
- They are redirected to their own bank’s login page (the same page they use for online banking).
- After they log in and give consent, the provider retrieves the account data and, if you choose, the current balance.
- Your system receives a confirmation that the account is valid and, optionally, that the balance is sufficient.
- The payment is initiated automatically.
Because the verification happens before the transaction, you avoid the classic “wrong IBAN” or “insufficient funds” errors that normally only show up after you have already sent an invoice.
A realistic example (fictional)
Emma runs a small bakery in Utrecht. She offers customers the option to pay monthly for a subscription box of fresh breads. Each month she sends an automatic incasso for €45.
-
Before open banking: Emma asks customers to type their IBAN into a form. One month, a new subscriber mistypes a digit. The first incasso fails, Emma’s accounting software flags the missed payment, and she spends an hour on the phone trying to correct it. Meanwhile, the bakery’s cash flow is tighter than usual because the €45 never arrives.
-
After adding AIS: Emma switches to a “Pay by Bank” button that uses an open‑banking provider. When the new subscriber clicks the button, the provider instantly checks the IBAN and confirms the account belongs to the subscriber. The balance check also shows that there is enough money for the €45 payment. The incasso goes through on the first attempt, and Emma never has to chase the customer.
The same principle works for larger amounts, for utility bills, or for any recurring service. The only thing that changes is the size of the risk you avoid.
Checklist: What you can do today
| ✅ Action | Why it matters |
|---|---|
| Ask for consent to use AIS | Without explicit permission you cannot read the account data. A short checkbox in the checkout flow is enough. |
| Choose a compliant open‑banking provider | Look for a provider that is certified under the Dutch PSD2 regulations and offers both payment initiation and account information services. |
| Add real‑time IBAN verification | This catches typos before the first payment is attempted, eliminating manual correction work. |
| Enable balance checks for recurring payments | Knowing the customer has sufficient funds reduces the chance of a failed incasso and the associated fees. |
| Integrate the checks into your existing invoicing or e‑commerce system | Most modern platforms (Shopify, WooCommerce, custom web apps) have plugins or APIs that make the integration straightforward. |
| Train staff on the new flow | A quick internal demo ensures everyone knows what to expect when a payment is declined and how to handle the exception. |
By ticking these items off, you turn a simple payment method into a proactive cash‑flow safeguard.
Frequently asked questions
Q: Do I need a developer to set up open banking?
A: Not necessarily. Many open‑banking providers offer plug‑and‑play modules for popular e‑commerce platforms. If you have a custom web app, a short development effort (usually a few days) is enough to add the API calls.
Q: Is my customer’s data safe?
A: Yes. The data is transferred over encrypted channels, and the provider never stores the full account details – only a token that your system can use for the specific transaction. The customer also logs into their own bank, so you never see their password.
Q: Will using open banking increase my costs?
A: Providers typically charge a small per‑transaction fee, similar to card‑payment fees. However, the savings from avoided failed incasso fees, reduced admin time, and lower fraud risk often outweigh the extra cost.
How IT Move NL can help
Implementing open‑banking checks may sound technical, but you don’t have to do it alone. Our Security & Protection team can set up a compliant AIS integration that fits your existing website or webshop, while our AI & Automation experts can tailor the workflow so the checks happen automatically, without extra manual steps.
We take care of:
- Selecting a trustworthy, PSD2‑compliant open‑banking provider.
- Connecting the provider’s APIs to your checkout or invoicing system.
- Configuring real‑time IBAN validation and balance checks.
- Ensuring the whole process complies with Dutch privacy regulations.
If you’d like to protect your cash flow, reduce payment‑related headaches, and keep your customers happy, get in touch with us today. A quick call is all it takes to start turning every direct debit into a reliable revenue stream.
Sources:

He/Him · AWS Certified Solutions Architect | Cloud Engineer @ Essent
Cloud Engineer at Essent B.V. with 10+ years of experience in the tech industry. AWS Certified, passionate about serverless architectures, Infrastructure as Code, and DevOps. Proficient in TypeScript, Python, and Terraform. Based in Amersfoort, Netherlands.
STAY IN THE LOOP
// Cloud, AI & DevOps insights — straight to your inbox.
No spam. Unsubscribe anytime.
// Related articles
Need help with your cloud infrastructure?
Our team of experts is ready to help you navigate the complexities of modern cloud architecture.
Get in Touch